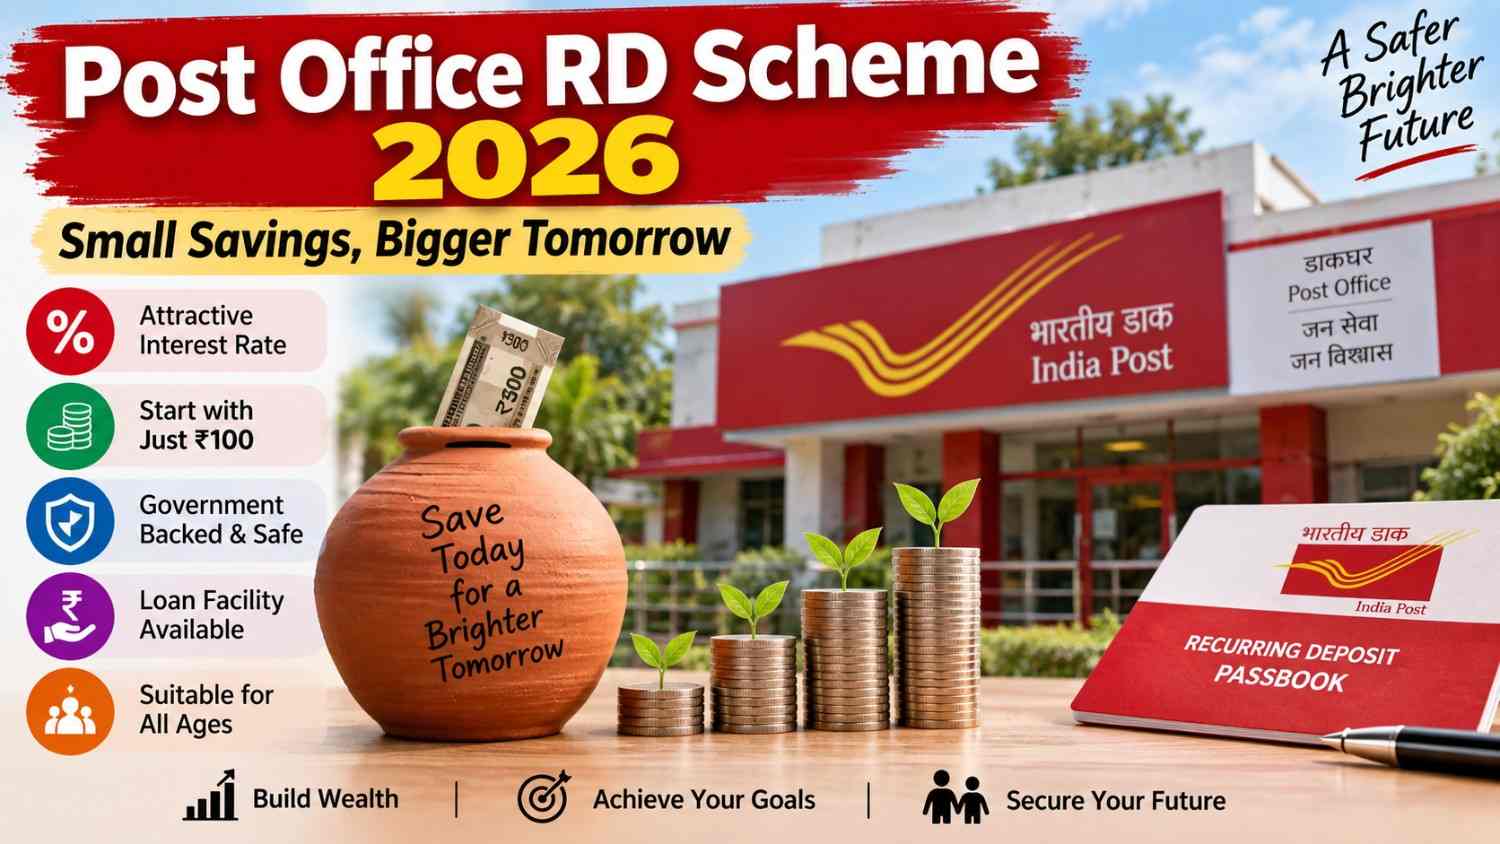
Post Office RD Scheme 2026: Saving a small amount every month can gradually build a sizeable fund. The Post Office Recurring Deposit (RD) is designed for exactly this purpose. Instead of investing a large lump sum at once, you deposit a fixed amount regularly and allow your savings to accumulate over the scheme’s 5-year tenure.
For investors who prefer a government-backed small-savings product and disciplined monthly saving, Post Office RD can be worth considering.
🏤 What Is the Post Office RD Scheme?
Post Office Recurring Deposit is a government small-savings scheme available through post offices.
Think of it as a disciplined version of a piggy bank: you deposit money every month, but your deposits also earn interest according to the rate applicable to the account.
The normal maturity period of a Post Office RD account is 5 years (60 monthly deposits).
💰 Post Office RD Interest Rate
The Post Office 5-Year Recurring Deposit rate has been 6.7% per annum, compounded quarterly, under the applicable small-savings rate notifications.
The Government reviews interest rates on small-savings schemes periodically. Therefore, anyone opening a new account in 2026 should verify the rate applicable on the actual account-opening date rather than assuming that an older published rate will continue indefinitely.
Post Office RD at a Glance
| Feature | Details |
|---|---|
| Scheme | Post Office Recurring Deposit |
| Normal tenure | 5 years |
| Monthly instalments | 60 |
| Interest | As notified by the Government |
| Referenced rate | 6.7% p.a. |
| Compounding | Quarterly |
| Minimum monthly deposit | ₹100 |
| Maximum deposit | No prescribed upper limit under the scheme rules |
| Loan facility | Available subject to conditions |
| Premature closure | Subject to scheme conditions |
| Account type | Individual/Joint/Minor accounts |
📈 How Does Interest Work in Post Office RD?
One major benefit of RD is compounding.
Interest is calculated according to the scheme’s prescribed method and compounded quarterly. In simple terms, your money earns interest over the investment period, helping the accumulated value grow over time.
However, unlike investing the entire amount on day one, RD contributions enter the account month by month. Therefore, every monthly instalment does not earn interest for the full five years.
This is an important point when calculating expected returns.
💵 What Happens If You Invest ₹1,000 Every Month?
Suppose you invest:
Monthly investment: ₹1,000
Investment period: 5 years
Number of deposits: 60
Total amount deposited: ₹60,000
At an annual interest rate around 6.7%, the final maturity value would be higher than the ₹60,000 you contributed because of the interest earned during the investment period.
The exact maturity amount should be calculated according to the Post Office RD rules applicable when the account is opened.
👉 Important: Online calculators may produce slightly different figures because the official scheme calculation, deposit timing, rounding and applicable interest-rate rules can affect the final amount.
🏦 Can You Take a Loan Against Post Office RD?
Yes. One useful feature of Post Office RD is the ability to obtain a loan against the account, subject to the applicable conditions.
After 12 instalments have been deposited and the account has continued for at least one year without being discontinued, the depositor may become eligible for a loan of up to 50% of the balance standing to the account’s credit.
This can be useful if you suddenly need funds but do not want to close your RD account.
💳 What Is the Interest Rate on an RD Loan?
The interest charged on a loan against an RD is linked to the RD interest rate according to the applicable scheme rules.
Under the stated rule, the loan interest rate is:
RD interest rate + 2 percentage points
For example, if the applicable RD rate is 6.7%, the corresponding loan rate would work out to:
6.7% + 2% = 8.7% per annum
Borrowers should check the current terms with the Post Office before taking a loan.
⭐ 4 Major Benefits of Post Office RD
1. 🛡️ Government-Backed Savings
Post Office RD is part of the Government’s small-savings framework. This makes it attractive to conservative savers who prioritize capital safety over market-linked returns.
2. 💰 Start With Just ₹100
You don’t need a large amount to begin.
A Post Office RD account can be opened with a monthly deposit starting at ₹100, making the scheme accessible to people who want to start saving with relatively small amounts.
3. 📅 Builds a Regular Saving Habit
Because deposits are made every month, RD encourages disciplined saving.
Instead of waiting until you have a large lump sum, you can gradually build savings through manageable monthly contributions.
4. 🏦 Loan Facility
Eligible account holders can obtain a loan against the RD balance after satisfying the required conditions.
This provides some liquidity without necessarily closing the account.
👨👩👧 Who Can Open a Post Office RD Account?
Post Office RD is not limited to salaried adults.
An account can be opened by an eligible individual, and the scheme also provides for joint accounts and accounts for minors according to the applicable rules.
A minor who has attained the prescribed age can also operate an account subject to scheme conditions.
Parents or guardians looking to build savings for a child may therefore consider the scheme, depending on their financial goals.
⏳ Can Post Office RD Be Closed Before 5 Years?
Yes, premature closure is permitted, but not immediately.
Under the scheme rules, an RD account may generally be closed prematurely after three years from the date of opening, subject to the applicable conditions and interest rules.
Because premature closure can affect returns, investors should ideally use RD for money they are reasonably confident they can leave invested for the intended period.
📅 Can You Continue the RD After 5 Years?
The scheme also provides an option to continue an eligible RD account beyond its original maturity period, subject to applicable rules.
This can be useful for savers who want to continue their disciplined monthly investment rather than withdrawing the maturity amount immediately.
⚠️ Things to Know Before Opening a Post Office RD
Post Office RD has several advantages, but it isn’t automatically the best investment for everyone.
Keep these points in mind:
- Interest rates on small-savings schemes are subject to Government notifications.
- RD returns are not market-linked, so you won’t participate in stock-market growth.
- Regular monthly deposits require financial discipline.
- Premature closure is subject to specific rules.
- Tax treatment should be considered based on the investor’s circumstances and prevailing tax laws.
- Inflation can reduce the real purchasing power of fixed-income returns.
Your choice should therefore depend on your time horizon, liquidity requirements, risk tolerance and overall financial plan.
🔑 Key Takeaways
Post Office RD can be useful for people who want to build savings through small monthly deposits rather than investing a large lump sum.
With a normal 5-year tenure, quarterly compounding and the possibility of starting with ₹100 per month, it offers an accessible way to develop a disciplined saving habit.
The loan facility can also provide liquidity after the account satisfies the required conditions.
Most importantly, check the latest Government-notified Post Office RD interest rate before opening an account because small-savings rates can change.
❓ Frequently Asked Questions (FAQs)
1. What is the Post Office RD interest rate in 2026?
The 5-Year Post Office RD has carried a rate of 6.7% per annum compounded quarterly in recent Government notifications. Since small-savings rates are reviewed periodically, check the latest official notification for the quarter in which you open the account.
2. What is the minimum investment in Post Office RD?
The minimum monthly deposit is ₹100, subject to the applicable Post Office scheme rules.
3. What is the maximum investment in Post Office RD?
The scheme does not prescribe a conventional maximum monthly deposit ceiling, although deposits must comply with the applicable denomination and account rules.
4. What is the maturity period of Post Office RD?
The standard maturity period is 5 years, involving 60 monthly deposits.
5. How much will I get by investing ₹1,000 per month for 5 years?
You will deposit a total of ₹60,000 over 60 months. Your maturity value will be higher after adding applicable interest. The exact amount depends on the interest rate and official RD calculation applicable to your account.
6. Is Post Office RD safe?
Post Office RD forms part of India’s Government small-savings system and is generally considered a low-risk savings option compared with market-linked investments.
7. Can I take a loan against my Post Office RD?
Yes. Subject to scheme conditions, an eligible depositor may obtain a loan of up to 50% of the balance standing to the account’s credit after completing the required period and instalments.
8. Can I close Post Office RD before maturity?
Premature closure is permitted after the prescribed minimum period, generally three years from account opening, subject to applicable conditions.
9. Is Post Office RD better than a bank RD?
There is no universal winner. Compare the prevailing interest rates, premature-withdrawal conditions, convenience, taxation, deposit protection/government backing and other terms before choosing.
10. Is Post Office RD a good investment in 2026?
It may suit investors who prioritize disciplined monthly saving and relatively low risk. Investors seeking higher long-term growth may also want to compare it with other investments appropriate to their risk profile.
📌 Conclusion
The Post Office RD Scheme 2026 can be a practical savings option for people who want to turn small monthly contributions into a larger fund over five years.
Its biggest attractions are straightforward monthly investing, quarterly compounding, a low starting amount and a loan facility subject to eligibility.
However, don’t choose an investment based only on the headline interest rate. Compare Post Office RD with alternatives based on your goals, investment horizon, taxes, liquidity needs and tolerance for risk.
Suggested Featured Image Alt Text: Post Office RD Scheme 2026 interest rate, monthly investment and 5-year maturity benefits
Disclaimer: This article is for informational and educational purposes only and should not be considered financial or investment advice. Interest rates, taxation and scheme rules may change. Verify the latest details with India Post and official Government notifications before investing.